Finding Freedom and Value in Rural Land: A Look at LandAndCreek
I have spent a good part of my adult life working with rural properties, helping people find parcels that fit their dreams and their budgets. What I have learned is that the path to owning land is rarely the same for two people, and the traditional mortgage route simply does not work for many. That is why alternative financing models like the one offered through LandAndCreek are worth a serious look. They address a real gap in the market for people who want a place to call their own without jumping through every credit-score hoop a bank requires.
Why Rural Land Appeals to So Many
The pull of rural land is powerful. It can be a weekend escape, a place to build a cabin, a site for a small farm, or just a quiet spot to park an RV and watch the stars. Over the past several years I have watched more people shift their priorities toward space, privacy, and self-reliance. The pandemic accelerated this trend, but it was already underway. People want room to breathe. They want a piece of ground where they can put down roots, literally and figuratively.
But the practical side of buying rural land is often more complicated than the dream. Zoning rules, access issues, water rights, and the cost of improvements can be daunting. And then there is the financing. Most banks are not eager to lend on undeveloped land. They see it as a higher risk. Loan terms are shorter, interest rates are higher, and down payments can be steep. That is where seller financing, sometimes called owner financing, becomes a lifeline. It allows the buyer and the seller to agree on terms that work for both parties, without a bank in the middle.
This model is at the heart of what LandAndCreek does. They offer rural land with owner financing, which means no credit check and low down payments. For a lot of people, especially those who have good income but a bruised credit score or a nontraditional work history, this opens a door that would otherwise be closed.
What Owner Financing Really Means for a Buyer
I have sat with families who were turned down by three different lenders before they found a seller willing to carry the note. The relief on their faces was unmistakable. Owner financing is not a gimmick. It is a practical arrangement where the seller acts as the bank. You make payments directly to them over an agreed period, usually with a fixed interest rate and a set term. At the end of the term, you own the land free and clear, or you refinance with a traditional lender if you prefer.
The big advantage is flexibility. Down payments can be as low as ten percent or even less. The seller is not bound by the same underwriting rules a bank follows. They care more about whether you seem like a reliable person than whether your credit score is above 700. That said, buyer beware: you still need to do your homework. Check the property's legal description, confirm there are no liens, and understand what utilities are available. A good seller will be transparent about these things. A site like LandAndCreek typically has detailed listings that cover access, terrain, and nearby amenities.
Another point worth considering is that owner-financed land often sells faster than comparable bank-financed properties, because the pool of eligible buyers is larger. That can be good for sellers who want a quick, clean transaction. For buyers, it means less competition and more time to find the right parcel.
Recreation, Off-Grid Living, and Building a Legacy
The site context for LandAndCreek mentions recreation, off-grid living, and building a legacy. Those three uses cover a wide spectrum, but they share a common thread: each requires a piece of land that is not just a vacant lot but a place with potential. Let me touch on each one.
Recreation
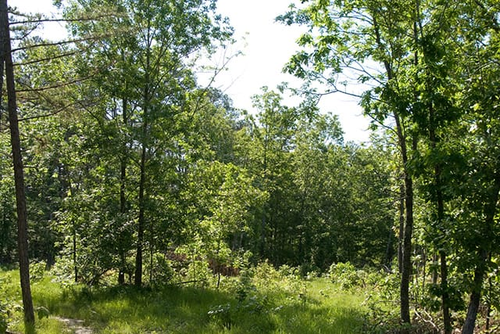
If you hunt, fish, hike, or ride ATVs, owning your own recreational land is a game-changer. You no longer have to rely on public land that may be crowded or restricted. You can set up a camp, build a shooting range, or just have a private spot where you can relax without a schedule. Many of the properties listed on LandAndCreek are in areas popular for hunting and fishing, with timber, creeks, and varied terrain. I have seen parcels that back up to national forest land, giving you access to thousands of acres of public land right from your own property line.
Off-Grid Living
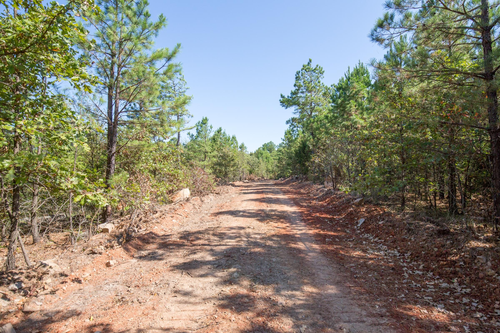
Off-grid living is about self-sufficiency. It means generating your own power, collecting your own water, and managing your own waste. It is not for everyone, but for those who choose it, the freedom is immense. The key is finding land with good solar exposure, a reliable water source (a well or a seasonal creek), and decent soil if you plan to grow food. LandAndCreek lists properties that are often raw and undeveloped, which is exactly what off-gridders want. You are not paying for improvements you will tear out anyway. You start with a clean slate.
I advise anyone considering off-grid land to spend a weekend on the property before buying. Camp there. See how the sun moves across the site. Check if there is a seasonal spring or a spot where you could dig a well. Talk to neighbors about groundwater depth and local regulations. A little reconnaissance saves a lot of regret.
Building a Legacy
This is the emotional side of land ownership, and it matters. A parcel of rural land can become a family gathering place, a homestead passed down through generations, or a base for a small business like a tree farm or a wedding venue. Legacy is not about the size of the property. It is about what you do with it. I know a couple who bought twenty acres with owner financing, planted a hundred fruit trees, and now host a small u-pick operation every autumn. Their kids help with the harvest. That is legacy.
LandAndCreek makes this kind of dream accessible by removing the credit barrier. You do not need perfect credit to start building something that will outlast you.
Practical Tips for Buying Owner-Financed Land
Over the years I have developed a short checklist I share with anyone looking at owner-financed land. It is not exhaustive, but it covers the most common pitfalls.
- Get a title search or at least a title report. You need to know that the seller actually owns the land and that there are no outstanding liens or claims.
- Walk the property boundaries. Survey stakes may be old or missing. Use a GPS app and a paper map to verify the corners.
- Check access. Is there a deeded easement to a public road? If the only access crosses someone else's land, make sure the easement is recorded and enforceable.
- Understand the mineral rights. In some states, surface rights and mineral rights can be owned separately. If you buy only the surface, someone else could come in and drill or mine later.
- Read the contract carefully. Know the interest rate, the term, the late payment policy, and what happens if you default. Some seller-finance contracts include a forfeiture clause that lets the seller take the land back quickly if you miss payments.
These steps are not hard, but they require attention. A good seller will welcome your due diligence. If they push back or get evasive, consider that a red flag.
How LandAndCreek Fits Into the Picture
I have been following LandAndCreek for a while, and what stands out to me is the clarity of their offering. They are not trying to be everything to everyone. They focus on rural land, they offer owner financing, and they make the process straightforward. The properties tend to be in the southeastern United States, an area with relatively low land prices, mild winters, and abundant water. That combination is hard to beat for someone looking for a recreational getaway or a place to live off the grid.
The site lists parcels with clear descriptions of terrain, access, and available utilities. Many properties have creek frontage or are near rivers and lakes. That is a big plus for recreation and for water access. The phrase LandAndCreek itself evokes that connection between land and water, which is a classic combination for a rural retreat.
One thing I appreciate is that they do not oversell. The listings are honest about what is there and what is not. If a property has no road access, they say so. If the only power is a mile away, they say that too. That kind of transparency builds trust, and trust is critical in a transaction that involves a long-term payment agreement.
Is Owner-Financed Land Right for You?
That is the real question, and the answer depends on your situation. If you have cash and good credit, a conventional loan might get you a lower interest rate. But if you are self-employed, retired, or rebuilding your credit, owner financing can be the only realistic path. It also gives you more negotiating power. You can often get a better price by offering a larger down payment or a shorter term.
The trade-off is that owner-financed land usually carries a higher interest rate than a bank loan, and the seller may not offer the same consumer protections a bank is required to provide. That is why you need to read every line of the contract and, ideally, have a real estate attorney review it. The cost of an attorney is small compared to the risk of a bad deal.
I have seen people lose their dream property because they did not understand the contract terms. I have also seen people succeed beyond their expectations because they took the time to learn the process. The difference is almost always preparation.
Final Thoughts From the Field
Rural land is not a passive investment. It requires work, planning, and a willingness to learn. But for those who take it on, the rewards are deep. You get a place that is yours, a piece of the earth you can shape to your vision. Whether you want a weekend hunting camp, a full-time off-grid homestead, or a family legacy property, the path starts with finding the right parcel and the right financing.
LandAndCreek offers a practical way to get there. By removing the credit check and lowering the down payment, they make land ownership possible for people who would otherwise be shut out. That is not a small thing. It is a real, tangible opportunity to build something lasting.
